
The financial brief.
One company. Four revenue engines. One listing path. PlayTown Ventures Sdn Bhd raises RM 7m — RM 6m ordinary shares (target; min RM 4m) at RM 1.00 for 60%, plus RM 1m RPS as a separate fixed-return instrument. Post-money RM 10m (OS-only, Option B; RM 11m fully diluted incl. RPS, Option A) · Ken 40% · External 60%. Rawang opens 2H 2027 → LEAP Market admission Y3 (governance only) → Transfer of Listing to ACE Y5 (FY2032) at RM 40m target mcap. Every number traces to Financial Model v2.1 (Y1 = FY2028).
Ken 40% · External 60%
~25% IRR
At target RM 6m raise · ~32% IRR
RM 8.4m by end-Y5 vs RM 7m raise
We didn't predict this. We watched it.
Six years operating MetaHub: every tournament, league and camp brought more than participants.
Parents came. Siblings came. Grandparents came.
Entire families arrived because of the programming — and the venue was built only for the player.
Disney proves the psychology. MetaHub proves the local demand. PlayTown is the productized solution.
Will it actually make money? Five questions.
The honest test of any pre-revenue thesis. Each answer carries its proof point.
CAVEAT: weekly visit cadence is a design target, not yet field-observed — a monthly cadence ≈ −50% to Rawang venue revenue.
| Level | What happens | Outcome for equity |
|---|---|---|
| 1 · Multiple compression | ACE prices at 10× Y5 core PAT instead of 13.4× → RM 30m mcap. | 2.25× MOIC / ~17.6% IRR at Y5. Entry at RM 4m pre-money is the protection. |
| 2 · No listing | Investors hold 60% of a private four-engine operator. | Dividend hold, not a wipeout — modelled 12-yr distributable RM 34.6m without Sites 4–6 (≈3.5× on the RM 6m line by Y12) — but illiquid. |
| 3 · Catchment failure | Rawang families don't come. | Asset-light engines soften but don't save the P&L. The unhedged tail every FEC carries. |
CAVEAT: Issuer projections, not independently verified; no listing is guaranteed.
A RM 22.5B sector. Three segments. One campus.
No single Malaysian recreation category describes PlayTown: the 187,100 sq ft hybrid combines Children's Entertainment Centre, Theme Park (water + dry) and Sports Facility formats. Sizing is built segment by segment so every figure traces to a source.
| Sub-segment | Size | Source · confidence |
|---|---|---|
| Indoor FEC | ~RM 200M | IMARC 2024 · public |
| Theme & Water Parks | ~RM 500–700M | Bursa operator filings + Legoland estimate |
| Sports Facilities | ~RM 500–800M | Issuer-modelled |
| Family Recreation & other | ~RM 300–500M | Issuer-modelled |
| Area | Population |
|---|---|
| Mukim Rawang | ~250k |
| N/W Selayang | ~130k |
| N. Sungai Buloh | ~100k |
| Kuang + S. Serendah | ~65k |
| Bandar Kundang | ~55k |
| Within 30 min of Bandar Tasik Puteri | ~600k · 130,000 families |
| Venue | Catchment | Visits/yr | Capture |
|---|---|---|---|
| Sunway Lagoon | KL metro ~8M | ~2M | ~25% |
| Lost World of Tambun | Ipoh + surrounds ~1.5M | ~1M | ~65% |
| Legoland Malaysia | JB · SG · S. Msia ~5–7M | ~1.5–2M | ~25–30% |
| Berjaya Times Square TP | KL metro ~8M | ~1.5M | ~20% |
| PlayTown Y7 target | ~600k primary + 3M accessible | 166k · RM 6.7M | ~19% primary · ~7% combined |
The Family Multiplier.
Traditional venues monetize the participant. PlayTown monetizes the Family Multiplier.
The campus keeps them there.
One company. Four revenue engines.
PlayTown Ventures Sdn Bhd (202501023878) is the operating, audit and Bursa listing entity — all one. It operates Rawang (RM 7m CAPEX, Lowyat lease), runs events, licenses the brand to third-party-capexed royalty sites and, post-ACE, owns Sites 4–6. One P&L, one cap table, one audit trail — no consolidation event between investors and the listing.
Rawang anchor Engines 1–2
- Engine 1 · Rawang Facility — sports courts + Wet & Dry + Soft Play. Y7 RM 4.90m gross; matures Y5–Y7, then modelled with honest novelty decay (Financial Model v2).
- Engine 2 · Rawang Other — F&B, merchandise, 8 gerai sub-lets, 7 retail units. Y7 RM 1.77m gross.
- Depreciation RM 700k/yr Y1–Y10 (RM 7m CAPEX / 10-yr straight-line)
- Company gross revenue Y1 RM 1.58m → Y7 RM 10.73m across all four engines
Asset-light engines Engines 3–4 + post-ACE
- Engine 3 · Multi-Site Royalty — 5% of licensed site gross revenue, third-party capex. Y7 RM 0.55m → Y12 RM 1.5m · 30 sites at maturity.
- Engine 4 · Events — Metahub already runs events.metahub.my (Malaysia SME Cup, DREAMS FH Cup live). Y2 RM 0.91m → Y7 RM 3.51m → Y12 RM 6.19m · 40% EBITDA margin.
- Post-ACE: owned Sites 4–6 (ACE-funded) — PAT line: Y6 RM 1.0m → Y7 RM 2.15m → Y8 RM 3.6m → RM 4.6m/yr Y10–Y12.
- RPS RM 1m — separate instrument, off the equity cap table (terms in the calculator below)
12-yr cumulative: revenue RM 103m · PAT RM 53.3m · distributable cash RM 59.3m → RPS coupons + equity distributions + Y5 ACE listing
From close to public listing — one dilution event.
Two shareholder classes at close — Ken and external investors — no option pool, no reserve. The only dilution before the public market is the 25% ACE float at Y5: holders retain 75% (external 60% → 45%; Ken 40% → 30%). LEAP Y3 issues no shares.
Round close
+ RM 1m RPS — separate instrument, off the equity table
LEAP (Y3) — governance only
Post-ACE (Y5)
What does RM 500,000 become?
Stake = ticket ÷ RM 10m post-money → × 0.75 after the Y5 ACE float → × scenario market cap. IRR is the implied annual rate to the exit year. Source: Financial Model v2.1.
ACE listing event breakdown
| Year | Exit at ACE (Y5) | Hold to Y7 | Milestone |
|---|
Y5 exit (ACE, FY2032). Mcap = scenario P/E × Y5 core PAT RM 2.98m. Base 13.4× ≈ RM 40m — below Genting Malaysia's 14× LTM and the FEC peer-set Q1 15.8× (see Thesis Q4); Upside 20× (RM 60m) in-band; Downside 10× (RM 30m) below-band. 3.0× shown is the pure equity sale — add pro-rata pre-ACE distributable cash Y2–Y5 (~RM 5.1m at 60%) and the Y5 total is closer to 3.8×.
Y7 hold (FY2034) — the 7.24× derivation (target raise; 6.59× at max). Cumulative distributable cash Y1–Y7 pro-rata (RM 18.78m company-level; 60% pre-ACE, 45% post-ACE) plus terminal equity at the same 13.4× on Y7 consolidated PAT RM 5.60m (mcap RM 75m). No re-rate: the uplift over Y5 is higher Y7 PAT plus the dividends a Y5-seller forfeits. Why 6.59× at max: at the RM 7m OS maximum, 11M total shares post-money vs 10M at target → external 63.6% pre-ACE (vs 60% at target), but per-RM MOIC drops to 6.59× because the fixed Y7 mcap (RM 75m at 13.4× P/E on PAT RM 5.60m) divides across more shares — the extra RM 1m raises absolute return, not the return per ringgit.
| Base 13.4× · hold to Y7 | Target raise RM 6m | Max raise RM 7m |
|---|---|---|
| External stake post-float | 45.0% | 47.7% |
| Terminal equity (× RM 75m) | RM 33.8m | RM 35.8m |
| Pro-rata distributable cash Y1–Y7 | ~RM 9.7m | ~RM 10.3m |
| Total return | ~RM 43.45m | ~RM 46.1m |
| MOIC / IRR | 7.24× / ~32% | 6.59× / ~31% |
Distributable cash build-up: RM 4.7m by end-Y4 · RM 8.4m by end-Y5 — exceeds the RM 7m raise before the targeted ACE listing. Company-level cash available for distribution, not amounts committed or paid to investors; distributions subject to Board declaration and Companies Act 2016 S.131. 12-yr cumulative RM 59.3m = PAT RM 53.3m + RM 700k/yr depreciation − RPS Y6 principal.
RPS (separate instrument). Per PS Term Sheet v10 Clause 4(i): −RM 1m at Y0, RM 80k Y2–Y5, RM 1.08m Y6 → total cash to holder RM 1.4m → expected ~1.4× / ~6.5% IRR (tentative). Unpaid coupons accrue and rank ahead of OS dividends; coupon and redemption depend on distributable profits and Board declaration under CA 2016 S.131 — not guaranteed.
Conditionality. ACE is the upside path, not the survival path: no listing → private dividend hold against the Model v2.1 12-year stream, illiquid but not a wipeout; catchment failure is the unhedged tail. 6-month Bursa moratorium applies post-ACE (see Capital Roadmap · Y5).
From Pre-launch to ACE listing.
RM 7m now → LEAP Y3 (FY2030, governance only) → ACE Y5 (FY2032, RM 10m raised at RM 40m). ACE proceeds fund Site 4 (RM 7m) + 2 satellites (RM 3m); licence sites pay 5% of gross on third-party capex, 30 at maturity.
Pre-launch round In progress
RM 7m via one MyStartr ECF campaign: RM 6m ordinary shares (target; min RM 4m, max RM 7m) at RM 1.00 + RM 1m RPS. Closes 30 November 2026.
Rawang opens — 2H 2027 Live operations
187,100 sq ft campus: Indoor Kampung, Outdoor Twin Towers + Bunga Raya, Splash Park, sports. Y1 gross RM 1.58m → RM 10.73m by Y7. KM approved 11 Aug 2026; BP submission in flight.
Events engine scales + royalty pipeline seeds
Events already run live at events.metahub.my (Malaysia SME Cup, DREAMS FH Cup). Licence pipeline seeds in parallel: third-party capex, 5% royalty on gross.
LEAP — governance only No capital raise Gate: Rawang operating + ramping
Governance and sponsor alignment, not a fundraise. Board discipline, reporting cadence and sponsor in place two full FYs before ACE — satisfying Bursa's LEAP-to-ACE holding expectation. No new shares, no consolidation event.
ACE listing + Site 4 build begins RM 40m target mcap · 25% dilution · RM 10m raised Gate: 2 FYs post-LEAP + sponsor comfort
RM 40m target mcap × 25% new float = RM 10m raised → Site 4 RM 7m + 2 satellites RM 3m. RM 40m = 13.4× trailing on Y5 core PAT RM 2.98m (defence in Thesis Q4 and IPO Basis). The primary exit event for this round's equity.
Site 4 opens (major, Rawang-equivalent) Gate: ACE proceeds funded
Sites 4–6 PAT line (Model v2.1): Y6 RM 1.0m → Y7 RM 2.15m → Y8 RM 3.6m → RM 4.6m/yr Y10–Y12. RPS principal redeemed end-Y6 from operating cash.
Satellites open — Site 5 (Y7 · FY2034), Site 6 (Y8 · FY2035)
Two satellites (~RM 1.5m CAPEX each) on the Rawang playbook. Y7 consolidated: gross RM 10.73m, PAT RM 5.60m.
Network at maturity — 30 royalty sites
30 royalty sites at maturity → RM 1.5m/yr royalty by Y12 on zero PlayTown capex. PAT RM 7.84m Y10 → RM 8.12m Y12; gross RM 11.29m → RM 11.61m.
One centre to a national network — LEAP Y3 → ACE Y5.
Rawang is Site 1. LEAP Y3 is the governance gate; ACE Y5 funds Site 4 + 2 satellites; the licence network builds to 30 sites by Y10–Y12.
Gross RM 1.58m · PAT −0.65m
RPS coupons begin
No capital raise
Sponsor aligned
Cum. distributable RM 4.7m
Core PAT RM 2.98m
Site 4 build begins
PAT RM 4.37m · RPS redeemed
Gross RM 10.73m · PAT RM 5.60m
ACE-funded
(5% of licensed gross)
PAT RM 7.84m
Gross RM 11.38m
12-yr cum. PAT RM 53.3m
Three layers. None of them the building.
A new entrant builds cold. PlayTown arrives with six years of operator infrastructure.
- MetaHub organizer relationships (6 yrs)
- Academy partnerships
- Coach networks
- School + corporate event clients
- League formats refined over 6 yrs
- Tournament scheduling know-how
- Holiday camp programmes
- The "what brings the 8th visit" engine
- Revenue share on attendee family spend
- Turnkey event operations (we run it)
- Venue hire subsidized by ancillary spend
- Organizers can't run a better event elsewhere
Where others failed — and how we don't.
Four named failure modes from public records and operator interviews — and the structural answer to each.
Per-visit pricing kills weekly-repeat economics
Outdoor-led FECs claim "weather-proof"
Mall-based FECs depend on mall traffic
One share class forces yield investors to take equity risk
Operating stress — the single-entity version
Rawang 30% under ramp: the RPS coupon is only RM 80k/yr, and the live events engine alone (RM 0.91m at 40% EBITDA by Y2 ≈ RM 0.36m) covers it before any Rawang contribution.
Equity absorbs compression through pricing, not principal: band-bottom ACE (10× → 2.25× at Y5) or a deferred listing (dividend hold against RM 34.6m modelled 12-yr distributable without Sites 4–6). Entry at RM 4m pre-money is the protection.
Not hedged: catchment failure (Thesis Q5, Level 3) — the reason pre-selling weekly cadence is the highest-value pre-launch action.
from the events engine alone
(Y2: ~RM 364k EBITDA
vs RM 80k coupon)
PlayTown Rawang — the architectural anchor.
Twin KLCC-inspired climber towers, a Bunga Raya secondary climber — the campus is a model of Malaysia: Indoor Kampung, Outdoor City, Splash Pulau.
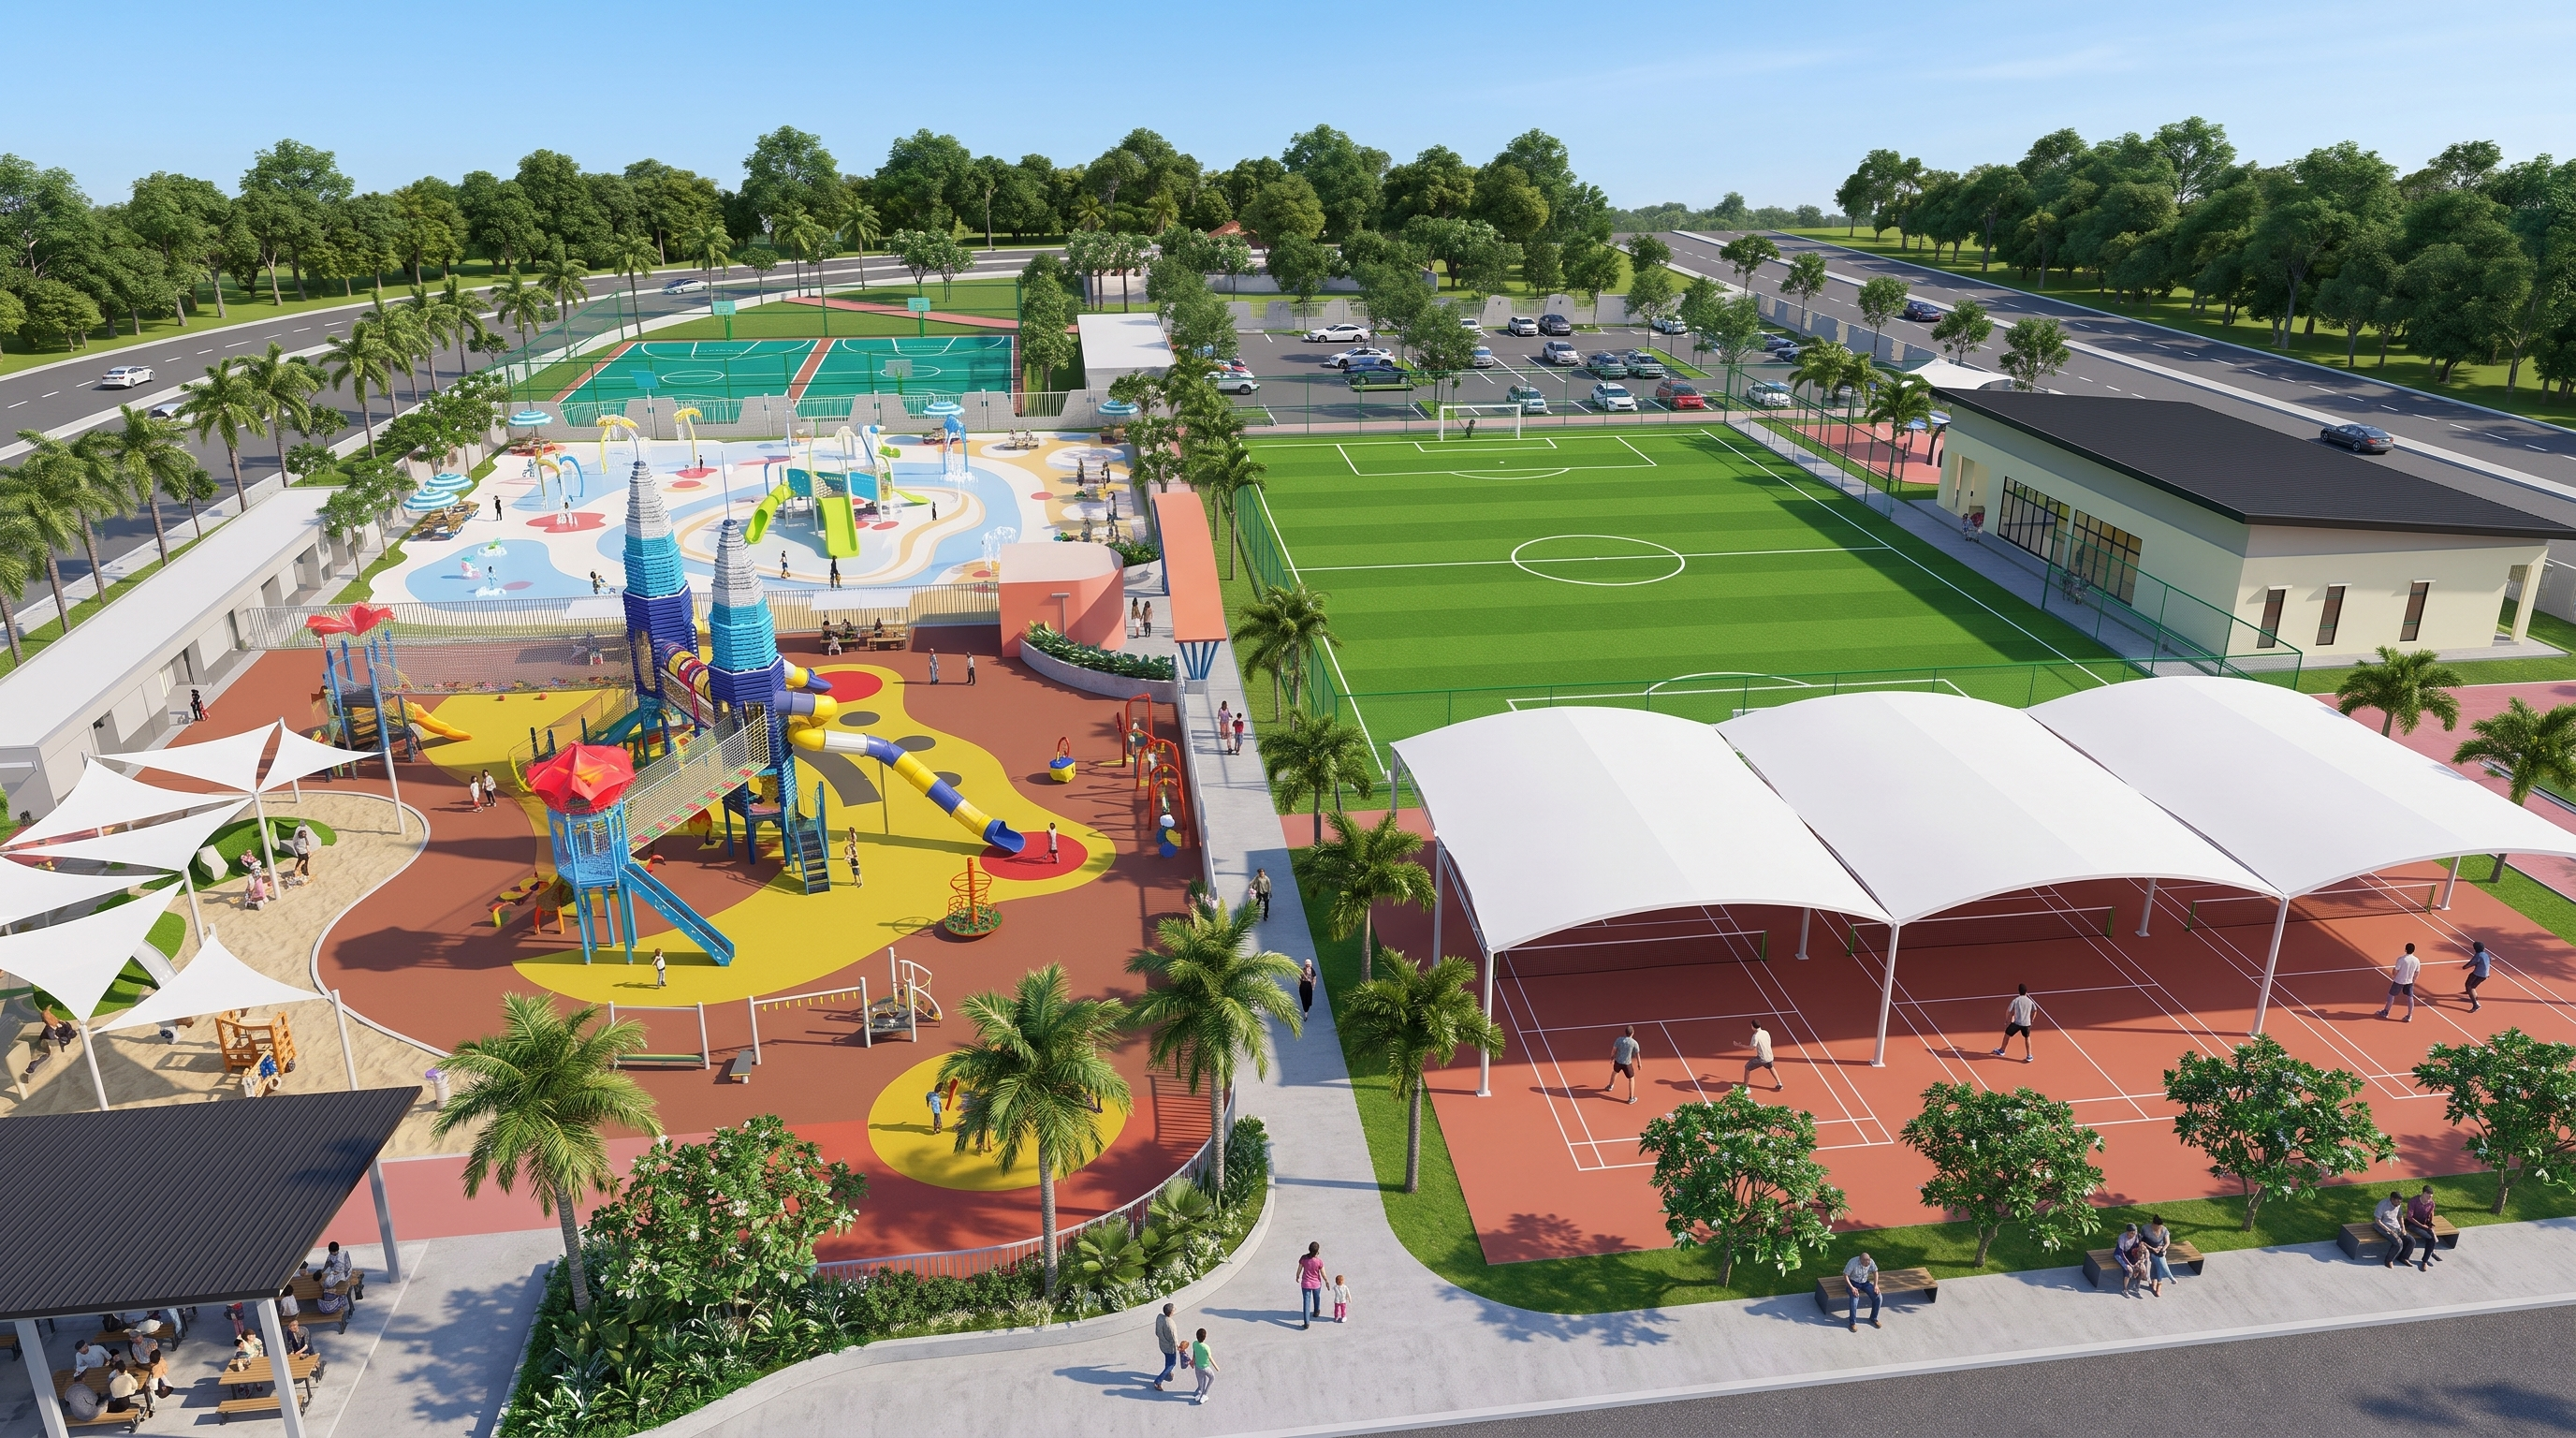
The bet at the centre.
Founder and landlord are locked in ahead of any external investor: Ken's 4,000,000 founder shares (the full RM 4m pre-money) under lock-up until the ACE listing; Lowyat's RM 6m site infrastructure plus membership pipeline. RM 10m of committed value alongside the round.
Zhong-Ken Ong ("Ken") · Founder/CEO
- Second-time operator. Previously founded MetaHub (2019–2025): RM 38.5m cumulative revenue · 575k+ annual users · 15–20% EBITDA margins. Pandemic-tested.
- 4,000,000 founder shares held directly — the full RM 4m pre-money at RM 1.00, for the IP, brand, three live apps and operating playbook. Same share class and price as external investors.
- 40% at the RM 6m target close → 30% post-ACE Y5 (50% at RM 4m minimum; 36.36% at RM 7m maximum)
- Founder lock-up: no transfer until the ACE listing, or 75% external shareholder written approval
- Disclosure — MetaHub & PlayTown structural separation: MetaHub is operational, restructured lean, with growing channels (academy partnerships, CCA programmes, advertising, event-agent revenue share); it survived 2025–2026 headwinds by cutting fixed cost and diversifying topline.
A legacy RCPS issued Sep 2020 (Covid period) remains under active discussion with the holder. MetaHub accrued rental obligations 2020–2022 and repaid all rental dues in full. The original redemption assumptions pre-date the restructure; the slot-based ceiling of football-field rental is the catalyst for the revised resolution path now in negotiation. (A live commercial matter; terms and timing are between MetaHub and the RCPS holder.)
PlayTown is structurally different — per-visit + membership ARPU, four engines, weekly cadence: revenue velocity an order of magnitude above slot rental. PlayTown's RPS sits inside PlayTown Ventures Sdn Bhd, ring-fenced from MetaHub, serviced from PlayTown's own operating cash.
Ken's commitments: MetaHub oversight (lean team), advising the Anyara Hills family development, and PlayTown as primary focus through the 2H 2027 open.
Lowyat Group · Anchor partner
- RM 6m site infrastructure investment (roads, utilities, frontage)
- 600–1,000 new homes/year bundle PlayTown memberships at handover
- Bandar Tasik Puteri — ~600,000 people within 30 min (DOSM Census 2020), 130,000 families
- Lease commitment aligned with 12-year operating model
- KM (Kebenaran Merancang) approved 11 August 2026 · BP submission in flight
- Selangor's highest median household income at RM 13,296/mo
Want the full data room?
Model v2.1 spreadsheet, signed Lowyat term sheet, cap table waterfall, construction schedule — after a 30-minute conversation with Ken.